Transcript:
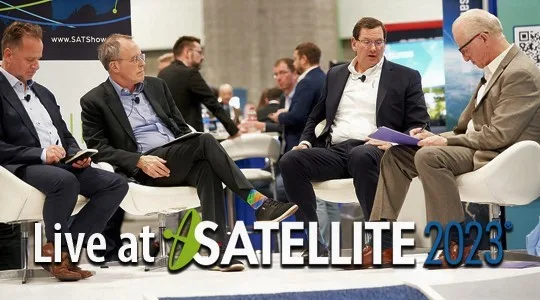
John Gilroy: Welcome to Constellations, the podcast from Kratos. My name is John Gilroy, and I will be your moderator. In the past, satellites have often been viewed by telecom service providers as the last resort of transport, and there’s a growing convergence here between these two worlds. In this podcast today, the discussion will be focused on the opportunities, the challenges, and the new business approaches taken by satellite and teleport operators to deepen integration with terrestrial telecommunication providers. We have a panel of experts behind me that will discuss the convergence of satellite and telecom, including the man with the fancy socks is Robert Bell, the Executive Director of the World Teleport Association. We have Guido Neumann, Chief Development Officer and President of the Access Network who needs to work on his socks and we have Stuart Daughtridge, Vice President of Advanced Technology at Kratos, and he’s got okay socks, better compared to mine. Okay, first question is for the man with good socks. Robert, telecom service providers have historically viewed satellites as a transport of last resort. You just said that. So why’s that been the case?
Robert Bell: Well, we earned that the honest way back when we first started doing significant amounts of cell backhaul, for instance. The capacity was extremely expensive. The dishes were big and expensive. All the other equipment was power hungry and expensive. And of course we weren’t following any telco industry standards. So how could they really love it with something that they did because they had to. They were told they had to connect some places and they would do it. But we certainly didn’t do anything to, shall we say, ingratiate ourselves to their business models.
Guido Neumann: When you look back 20 to25 years ago, all the big telcos have really seen satellite as a niche market. They’re focused on the fiber network, terrestrial network. Many big telcos in Europe have even sold their satellite divisions. And as Robert Robot said, at that time, satellite was no future. It was a niche market. But this has now fortunately, changed.
John Gilroy: Stuart, I used to be a redhead, and there’s old jokes about the redheaded grandchild. The redhead stepchild. So why is telecom always been like the redhead stepchild? It’s been in the back burner.
Stuart Daughtridge: Well, one of the reasons is satellite didn’t focus on supporting telecom. I mean, satellite’s business was broadcast. That’s where most of the money was made, that where the focus was. And so the satellite industry didn’t make a great effort to be a great friend to the telco world because that wasn’t where the majority of their business was.
John Gilroy: So Tom Cruise question. Show me the money, huh?
Stuart Daughtridge: Yeah. Exactly. And the money was from broadcasters.
John Gilroy: Yeah. Well, good, good, good. And it’s changing a little here. Yeah. Guido got a question for you. What are the factors driving satellite industry to modernize and better integrate with mainstream global telecom networks?
Guido Neumann: Yeah, that is a interesting and good question. And it depends on different factors. So on one hand, pricing is very important. So the costs, costs have gone down automatically on the capacity and on the terminals, which is very important to have a lower entry in the market. Yeah. Another thing is that also the technologies have involved. We had access. We are running several very big GSM back holding, cellular back holding networks in the Americas. And here you see, you have to provide, or not only the connectivity to the towers, you have to manage the towers. That means you have to help the MNOs to manage the towers. Maybe on one tower there’s less traffic. You can bring the capacity to another tower. In this regard, you are saving overall capacity, you’re saving money. So that means you are helping the telcos by providing not only creativity, but value added services. And I think, I’m sure this trend will go on to that becoming more and more very important critical factor for telcos.
John Gilroy: Robert, do you have anything to add?
Robert Bell: Yes, I do. I mean, there’s the MNOs, particularly mobile network operators know exactly what they’re paying for back haul. And I was told that sort of a magic number out there of about three gigabytes per second. Per month. Per month, sorry, $3 per gigabit. And if we can get down there, suddenly we become competitive. Well, we’re getting into that zone. But the other thing is just that the business has changed. Broadcast is now generally speaking, in most places, a fairly stagnant business. It’s still growing in some areas for satellite operators, but it’s not going to be the engine that Stuart was talking about. Have to find growth someplace else.
John Gilroy: Now, Stuart, we’re here in Washington, DC. Throw a stone. You feel federal agencies, there’s all kinds of acronyms around here. DEA, FBI and everything else. Well, the new acronym in town is MNO. We got to talk about MNO. It’s mandatory here at the conference here. So what technologies does the satellite industry need to adopt to better integrate with telecom and MNO networks?
Stuart Daughtridge: Yeah, so I mean, basically we have to make it easy to work for the telcos to use satellite. And so we need satellite to look transparent to the telcos. So we need to adopt their standards. We need to adopt their technologies that they use in their ground infrastructure. And by doing that, we can actually make it easy for them to use satellite. I mean, if you look at a telco right now who does a lot of satellite capacity, satellite services, they’ll actually have a completely separate group that manages their satellite services, separate from all of their other services. That’s a problem. We have to make it so that their normal transport group that manages their existing services can do that right through a satellite. And that’s by adopting their standards, whether be meth or 5g. It’s, and basically making it easier for them to orchestrate services, right through a satellite network.
John Gilroy: Robert, if I remember correctly, one of the office companies like Office Depo or maybe Staples had the easy button. Remember they hit the easy button and use the phrase there, got to make it the easy button. So transparency, easy. Is that the key you think?
Robert Bell: It is, and there’s an underlying transformation that has to happen. We’ve all heard too many times the words digital transformation. Well, this industry is not really transformed digitally at the same pace, certainly as the telecom and the internet industries have done. And if we’re going to do business with them in a transparent way, we’re going to have to get on that same playing field, otherwise it’s not going to work.
John Gilroy: So Guido, do they have an easy button in Germany?
Guido Neumann: We work on that like office. Yeah, yeah. No, but I fully agree. The business have to become more simple to understand for the traditional telcos. So when they configure or design their networks, they have to always have satellite in mind as a value option compared to the classical options. So when they can even see the advantages to reach more rural areas where there’s no fiber, where they can use satellite, but then they first have to understand how satellite works, and we can help here to make it easier, the terminals, the usage, and how to understand how to design the satellite network.
John Gilroy: Well, I mentioned we’re in Washington, DC. If you go up the road a bit, you run into someplace called NIST, a lot of standards up there. In fact, that was a word that was just tossed about here standards. And I have something very profound to say about standards. Standards are like toothbrushes. Everyone wants to use their own. So standards are tough in some industries, maybe even in the satellite industry. Let’s talk about standards here. Question for Robert, terrestrial carriers and mobile network operators, MNO, mobile network operators work in a world of standards. So how is satellite technology adapting to that need today?
Robert Bell: Very unevenly. The industry’s never been known for standardization. In fact, a whole economic base for most of its history has been about locking somebody in. It’s been about having proprietary technology standard. It’s about having a carriage trade business where you charge a lot of money for limited bandwidth. Those days are gone, and we’re still now adapting. What we find is that most satellite and teleport operators are still just beginning to crack that nut, if you will, of integration with telcos. They don’t really know quite how to do it, and they’re not sure how to rethink their networks for this new world. And in all of that, how to earn a worthwhile return on investment, right? Because you’re going to keep doing your legacy business as long as you’re getting a good return on it. In terms of mindset, I don’t think we’re actually all that far advanced from the days when we had to come up with a whole lot of workarounds in order to back haul cell traffic in 3G and 4G. But there’s no question about where we’re going because right now, any teleport operator, which is the world I’m most familiar, familiar with that is focusing increasingly on transporting IP as opposed to broadcast. They are under incredible pressure because they’ve got to digitize, they’ve got to virtualize, they’ve got to automate, they’ve got to orchestrate to handle the exploding volume and the exploding complexity of the traffic they’re carrying. So they’re getting pushed into the world, whether they’re ready or not.
John Gilroy: Stuart, I’ll ask you if you’ve ever been up to NIST and talk to the people up there or not, all kinds of clocks up there. I know they’re accurate. So tell us about standards and satellites here.
Stuart Daughtridge: Yeah, so it’s really interesting that 5G is fascinating because they’ve started to actually incorporate satellite into the 5G standard with the NTN portion of the standard release 17. Now you have a telco or mobile industry standard that actually incorporates satellite and satellite special needs into it. That’s a huge transformation, and that was driven by the satellite industry actually getting involved with the 5G standard and starting to drive those changes. So it’s the mindset change that Robert mentioned, it’s happening in the industry. But I say the other thing that been fascinating is the DIFI specification got started a little over 18 months ago, and now it has 60 members in the industry. It has support from all the U.S. major, U.S. military government, and government groups. So just the adoption and the speed of that standard just shows the mindset switch that you’re seeing in the industry where the industry’s recognizing that standards are the key to growth.
John Gilroy: So Guido, I think, if I’m not mistaken, 5G originated with a company in Sweden, I think with Ericsson, a guy named Boof. And so what do you think about these standards and whole idea of communications and standards developing here today?
Guido Neumann: Not to mention, today, the standards are really defined by the telcos for the 5G and cellular, and currently we are satellite operators or service providers. We are adapting that, which means we are creating our networks, our technology to provide to our services. In the Americas, we are running not only 5G, we are running still 4G, 3G networks in Africa. They are not far away from 5G. That means we have to be prepared and using our technologies to serve all these different markets. And when it’s only, let’s say, looking into the poor connectivity, it doesn’t matter for us. If you connect the 4G or 5G network and we look behind the connectivity to all the equipment that require the kind of different hubs we have, we are still a bit away from poor standards because we then have to select if it’s a system like Gilat or iDirect, or new app only to mention this, there are more technologies. On the other hand, we have discussions here about LEO, MEO, GEO, and a hybrid network. So we are far away from really standards here, but I don’t see it so much required because we can currently use our technologies with all the available standards, what the MNO requires.
John Gilroy: Robert, I want to ask you about DIFI. Are you surprised with how successful DIFI’s become just in a couple years here?
Robert Bell: Yeah. I’m very, very pleasantly surprised. This DIFI stands for digital intermediate frequency interoperability. Rolls off the tongue, doesn’t it? And it’s such a simple idea that all the devices that are actually hooked together should get their analog content digitized as soon as possible and be able to exchange it. And right now we’re in a world of proprietary standards where that’s hard. So this is a very fundamental building block. I’m thrilled that kind of uptake has happened. It just tells you that the major users, not necessarily all the people who are doing the service provision, but the major users really want this. And that’s of course, when your customer wants something, that’s when you got to move.
John Gilroy: Guido, yesterday, I did an interview right at the stage here and we used the term orchestration, interoperability, working together standards. So what challenges does the satellite industry face to becoming more integrated with telecom networks?
Guido Neumann: Yeah, exactly what I mentioned earlier. When we look in the future, we have to create stable solutions, hybrid networks where the user does not see the difference if there’s maybe a GEO behind or a mirror or LEO behind. And the user is also not interested what kind of hardware manufacturers behind here. We have to work on the next years that this becomes really simple. Again, back to the simplicity, easy things to do, and we have to create a standard in the background. So that is very important for us to do that.
John Gilroy: Robert, what are the obvious challenges that you see in this transition?
Robert Bell: Well, I’m very interested in what you said, Guido, because is that the most efficient way or should we be actually trying to rebuild what we’re doing to adopt those telco standards? I don’t know what the answer to that question is, but it sounds very complex what you’re talking about as opposed to trying to allow the telco standards to flow into our processes. What have you thought about that at all in terms of the future? I mean, right now we have to work with what we’ve got, but in the future, what direction should we take?
Guido Neumann: Yeah, I think the future, let’s say the telco market, the cellular backhaul markets for connectivity to the phones, to Samsung, the iPhone of the world to provide internet, but also voice is still driven by the telcos. And they are still, sorry. They are the powerful suppliers behind. And they give us the direction where we have to go.
Robert Bell: They’ve got 99% of the market. Yep. That’s pretty powerful.
John Gilroy: Yeah. You want to chip in with this, Stuart?
Stuart Daughtridge: Highlight what Guido said, that when you have an existing infrastructure, it’s hard to move to new technology and it’s hard to adopt new standards and new capabilities, but the fact is the industry’s going to have to make that adjustment when they turn up new services and when they have opportunities to do the upgrades.
John Gilroy: So with this growing convergence, what market opportunities do you think will spur collaborations between telecom service providers and satellite operators?
Stuart Daughtridge: Well, I think it, there’s two strong market forces that are going to create this to happen. One, the satellite operators need it. I mean, as Robert said, the satellite industry is 1% of the IP transport market today. So we’re tiny, and if we want to grow to 2, 3, 4, 5% of that market, that’s where the growth in the industry is going to come from. And so the satellite industry has to play better with the telco, telecommunications market. But the interesting thing now is talking to the telecommunications operators, they all of a sudden need satellite because they’re getting pushed really hard by the regulators to connect the unconnected. And they can’t do that without satellite. So all of a sudden, the regulators are way more interested in playing nicely with the satellite operators than they were 5, 10 years ago. And so the satellite operators need the telcos, and the telcos now need the satellite operators. So with those two forces, you actually it’s like, what’s going to happen? Because it has to happen for both industries.
John Gilroy: I don’t want to turn this into a federal talk, but there’s a recent amount of money, a billion dollars has been dedicated to infrastructure upgrade in the United States specifically to connect the unconnected. And that’s exactly the words out of the executive order, isn’t it?
Stuart Daughtridge: Yeah, exactly.
John Gilroy: The Constellations Podcast was launched back in 2017. It was a small step for man, but a giant leap for podcasting. Today, thousands of people from all over the world listen to Constellations and thanks to you, we’ve grown into more than just a podcast. Sign up for the Constellations newsletter to receive articles on current industry issues, podcast summaries and contributed blog posts at constellationspodcast.com.
John Gilroy: When he talks around the word billion, you got to talk about something called TAM, total addressable market. And we talked about 1% here, 1% there. We got to do a little TAM talk here, a little total addressable market and where we can grow into that. And it may be an opportunity for everyone in this building. So, Guido, satellite service providers today have a very small share of the overall telecom market. 1%, huh? Maybe less. So if they start to work more synergistically with telcos, how much more market share could they capture? What’s the tam here, buddy? What are you looking at?
Guido Neumann: I will not provide just a figure, but I will maybe make a good example. I was two weeks ago on the Mobile World Congress in Barcelona. It’s one of the biggest show in this regards. I can tell you 5 to 6 years ago, there were no satellite operators at all. There was maybe a Jeep with a Kymeta antenna. Two weeks ago, all the operators had a big booth there. Hispasat, our mother company also, the LEOs were there, OneWeb, SpaceX. So you can see, and if this trend will, let’s say on the exhibitions will reflect also our market share, I see a good chance that we are also reaching a two digit figure on the long term. Coming back also to this unconnected areas. When you look to Africa and South America, Latin America, the business case has to be closed. If a telco makes no money, they will not put the tower somewhere, if there’s only a small village. But if we were satellite will change our products in the future and make it more attractive that the business case will close even for a small village in Africa, in Latin America, all over the world, then this will have a lot to expand the networks. And if they make money, they make money on the value added services, then the people can do all the streaming application, et cetera, et cetera. So it’s a bit price driven, but again, I’m very optimistic and positive. A two digit figure in the all over market could be possible.
John Gilroy: Well, Robert, maybe you should start a podcast and have it called TAM talk. So it comes to TAM talk. What is the total addressable market here? Where is the explosion going to be?
Robert Bell: I obviously have no more idea than Guido does, but I love his double digits. I think of it this way, we’re 1%, if we go to 2%, we’ve doubled the size of our industry. We’ve just added $20 billion. Can we at least make that the ambition? And from there on the sky’s the limit.
John Gilroy: So sort of football coach would say, can you give me just another touchdown? Can you give me one point? Give me six points.
Robert Bell: Exactly.
John Gilroy: Give me six points. So what you talking six points here?
Robert Bell: Yeah. I think there’s a huge amount of opportunity in just helping the telcos solve their problem. And yeah, price point matters and technology matters, but boy, the opportunities are huge.
John Gilroy: Well, we have a timing question here. We did the TAM talk. Now a timing question here. Question for Robert. Looking ahead, how long before satellite networks become more integrated into the mainstream telecom network and what impacts will that bring?
Robert Bell: Well, do you want my optimistic answer or my pessimistic answer?
John Gilroy: Realistic answer, buddy. Realistic.
Robert Bell: Okay. It all depends frankly on how scared we get. If we get sufficiently frightened by the fact that our cash cow and broadcast is stagnant and declining and we want to grow our business, and then we’re going to really get serious about it. I was thinking about this question beforehand, and I remembered a conversation I had probably about 10 or 12 years ago with a guy named Ed Horowitz. With that point was the president of SES America, and he was complaining about the fact that the Moore’s law is transforming everything except us. It still at that time, it was taking us four years to build a satellite. And Moore’s law says, we’re going to double what we’ve got in every 18 months. Fast-forward those 10 or 12 years, and look how, look, how many satellites are being launched right now. Look how fast that problem has been solved as being addressed. So I don’t think there’s anything we can’t fix. There’s just a question of if we’ve got the motivation.
John Gilroy: So Guido in Germany, do they have cash cows or just regular cows?
Guido Neumann: Milk cows. No, let’s say I think we are on the right way. It takes the time. Yeah. I think a car was not mainstream in 1915. Today it’s mainstream. When you look to the smartphones when we started, or the wireless phones, big box you have to carry, it was not mainstream, today it’s mainstream. So again, but we see the trends, we see the trend on the launches of satellite. We see the trends of the different types of satellite, high strip port, different orbits, smallsat, cubesats . Now they build smallsats for GEO and the satellites have more capacity. So the determinants are getting cheaper and smaller. When you saw here the speech from Amazon and you saw this coffee cup and the antenna is similar, a bit bigger, but we are in the right direction. But it takes a while. So I think when we really become a standard, in regard to your question, I think in five years onwards, we are maybe coming closer.
John Gilroy: Well, Stuart, you’re the last one I got to ask you. Ask your percentage question, got to ask you the timing question back to the future, or what were you looking at here?
Stuart Daughtridge: I think it’s going to actually think it’s going to be a little quicker than the five years solely because the need is great. You know, got to replace your revenue that you’re losing in broadcast. You got to find growth in the IP transport market and integration with telco. The faster you do it, the greater your growth potential. And so I think it’s going to be, I think the uptake is, and I think the industry now recognizes that they have to do this. So I think it’s not a matter of if and when and once the industry puts their mind to it, I think it will happen relatively quickly. So maybe three years.
John Gilroy: In the podcast we did yesterday, I talked about public-private partnerships. And I want to may hit on that and ask each one of this one. Now, there have been a number of partnerships and collaborations announced recently between satellite and telecom players. So Stuart, do you see other announcements in strategic areas on the horizon? Any ships coming together here?
Stuart Daughtridge: Well, yeah, there’s a couple of announcements probably for the show even. And so I think that absolutely you’re going to see continuing announcements. Couple years ago you saw announcements about satellite operators and cloud providers teaming up and around the same time you saw a lot of announcement between cloud providers and telcos meeting, teaming up. I would not be surprised to see more with satellite operators in Telco teaming in the future. And I think just there’s going to be a natural integration of the industry as we go through this transformation.
John Gilroy: So Robert, one plus one is three for 3%, or where do you see the partnership going?
Robert Bell: Well, no, I agree very much with that point of view. Largely because it’s a risk reduction strategy. If we establish a firm partnership, if I’m a satellite operator and I establish a strong partnership with a telco, we’ve both just reduced our risk. We’ve committed to integrating ways that might be risky for either one of us to do alone. So yeah, I think you’re going to see a lot more of them.
John Gilroy: So it seems like Europeans are more collaborative than Americans. I don’t know if that’s true or not. What do you think about the idea of partnerships and collaborations?
Guido Neumann: Yeah, let’s say next the two you have mentioned, on one hand the satellite operators and service providers are still seeing that there will be more conglomerates. We even also maybe see M&As in regarding to telcos. Telecommunications company T-Mobile are teaming up with Starlink and there are many other things which are already announced. I think here you have from the multiple orbits, telcos, phone manufacturers, service providers, satellite operators, teaming up together, merging together. I think it will be a lot of interesting things coming up here.
John Gilroy: That’s great. I’d like to thank our guests, Robert Bell, the Executive Director of the World Teleport Association, Guido Neumann, Chief Development Officer and President of Access Networks, and Stuart Daughtridge, Vice President of Advanced Technology at Kratos. Thanks for your insight, gentlemen.